What is the market overview of the Team Sports Recovery Drinks Market?
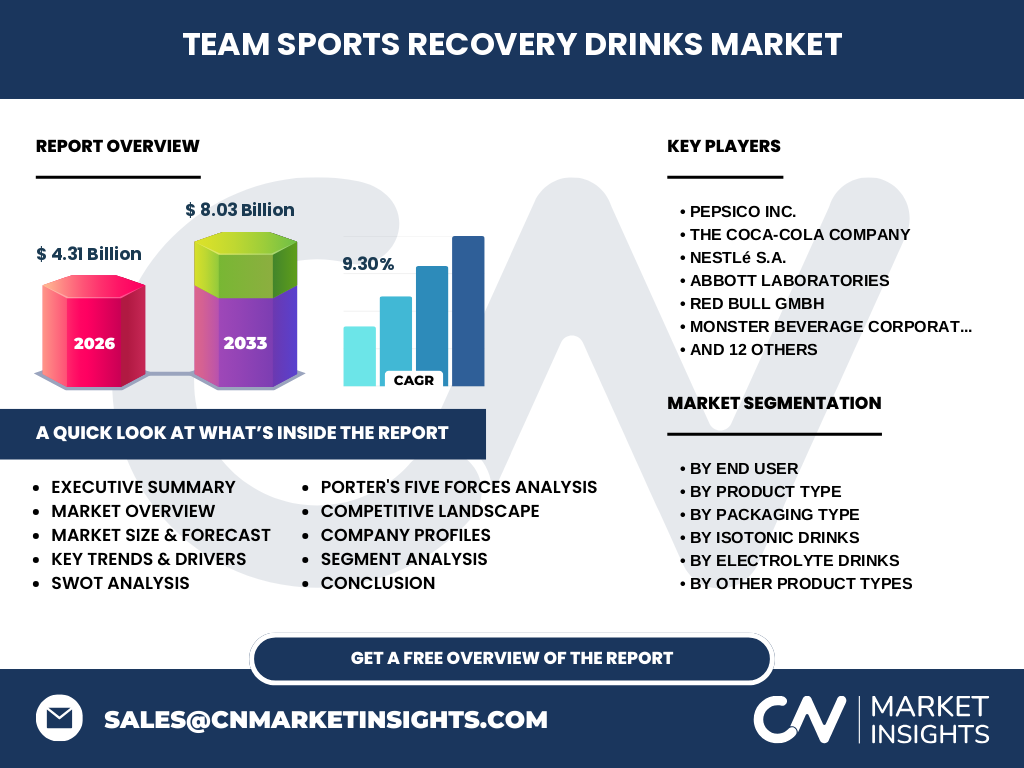
Our analysis indicates that the Team Sports Recovery Drinks Market market size reaches 4.31 Billion in 2026. This sector encompasses isotonic, protein-based, and herbal formulations tailored for athletes in football, rugby, and basketball. Regulatory oversight by bodies like the EFSA and FDA strictly governs functional claims regarding muscle repair and glycogen replenishment.
What are the structural growth drivers, restraints, challenges, and opportunities shaping the Team Sports Recovery Drinks Market industry trends?
The primary catalyst is the professionalization of collegiate and amateur athletics, driving demand for rapid rehydration. Conversely, supply chain bottlenecks for key raw materials like whey isolate pose structural restraints. Strategic opportunities lie in cold-chain logistics innovations moving through major distribution hubs in Rotterdam and Singapore.
Emerging trends and growth patterns in the Team Sports Recovery Drinks Market analysis
Clean-label formulations and organic ingredients dominate consumer shifts. Natural Electrolyte (Coconut Water-Based) and adaptogenic additions like ashwagandha are capturing significant market share. Brands are moving away from artificial colorants, favoring botanical extracts to appeal to health-conscious team sports participants.
How did the COVID-19 pandemic impact the Team Sports Recovery Drinks Market and shape its recovery trajectory?
Pandemic-related lockdowns severely disrupted institutional sales through schools and colleges, causing a temporary contraction. However, the subsequent post-pandemic recovery accelerated direct-to-consumer online retail channels. Our research shows that supply chain diversification has since become a priority for major beverage manufacturers.
Competitive benchmarking and strategic dynamics in the Team Sports Recovery Drinks Market
The landscape features high market concentration led by giants like PepsiCo Inc., The Coca-Cola Company, and Nestlé S.A. Alongside these multinationals, disruptive entrants such as Prime Hydration LLC and Celsius Holdings Inc. leverage targeted social media marketing to capture youth demographic segments in team sports.
Executive summary of key findings for the Team Sports Recovery Drinks Market
Our comprehensive report reveals a robust valuation of 4.31 Billion in 2026, scaling toward strong future projections. The integration of functional ingredients and personalized nutrition packs represents the highest-conviction investment thesis for stakeholders navigating this competitive beverage ecosystem.
What is the long-term market forecast for the Team Sports Recovery Drinks Market from 2027 to 2033?
The data projects the market to surge from 8.03 Billion by 2033, expanding at a remarkable CAGR of 9.30%. This trajectory is underpinned by rising disposable incomes globally and increased institutional spending on athletic infrastructure across professional and amateur franchises.
Segmentation analysis by end-user, product type, and packaging type
Categorization spans Professional Teams, Amateurs, and Schools And Colleges. Product lines encompass Isotonic Drinks, Protein-based Drinks, and Herbal Recovery Drinks. Packaging preferences heavily favor recyclable Bottles and eco-friendly Pouches to meet corporate sustainability mandates.
Geographic distribution and performance across regional sectors
North America remains the dominant revenue generator due to massive collegiate athletic infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest regional growth rate, propelled by expanding urban middle classes and government initiatives promoting organized team sports in nations like China and India.
In-depth regional review of key markets
European markets are heavily regulated by the European Food Safety Authority, restricting unauthorized health claims. In contrast, the Latin American market relies heavily on local distribution networks via convenience stores, favoring cost-effective powder mix recovery drinks over premium ready-to-drink formats.
Company profiles and strategic positioning of leading market participants
Industry leaders like Abbott Laboratories and Glanbia plc focus on science-backed protein efficacy. Meanwhile, niche innovators such as Skratch Labs LLC and Torq Fitness Ltd. emphasize clean-label electrolyte replenishment, carving out defensible moats among endurance-heavy team sports athletes.
Porter's Five Forces analysis of competitive intensity
The threat of new entrants is moderate, constrained by high capital expenditure requirements for manufacturing scale. Buyer power is high due to fierce supermarket shelf-space competition among heavyweights like Monster Beverage Corporation and Red Bull GmbH.
SWOT analysis highlighting internal capabilities and external pressures
Strengths include established global distribution channels. Weaknesses involve high marketing expenditure vulnerability. Opportunities emerge in plant-based protein innovations, while threats center on tightening regulatory scrutiny regarding sugar content from agencies like the World Health Organization.
Value chain analysis from raw materials to end-users
Value creation begins with agricultural sourcing of whey, pea isolates, and botanical extracts. Processing occurs in automated bottling facilities before shipping through major maritime ports, ultimately reaching end-users via supermarkets, specialty stores, and specialized online retail platforms.
Investment insights and high-potential growth areas
Investors should allocate capital toward personalized nutrition packs and subscription-based recovery kits. These segments exhibit superior customer lifetime value metrics and protect margins against commoditized basic electrolyte replenishment drinks.
Conclusion and key strategic takeaways
The sector presents compelling growth anchored by a 9.30% CAGR. Success requires balancing functional efficacy backed by clinical research with agile supply chain management to navigate fluctuating raw material costs for ingredients like magnesium and potassium.
Research methodology detailing data triangulation and validation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary C-suite stakeholder interviews with executives from Britvic PLC and GU Energy Labs, and secondary macroeconomic indicators from global sports nutrition federations.
Scope of the report, coverage parameters, and analytical limitations
This report evaluates global sales data across retail and institutional channels, excluding direct-to-consumer gray-market transactions. Geographic scope encompasses North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa from 2026 through 2033.
Recent developments, corporate announcements, and strategic partnerships
Recent market activity highlights increased M&A engagement, with established players acquiring clean-label startups. Partnerships between beverage formulators like MusclePharm Corporation and professional sports leagues underline the ongoing race for official hydration supplier designations.